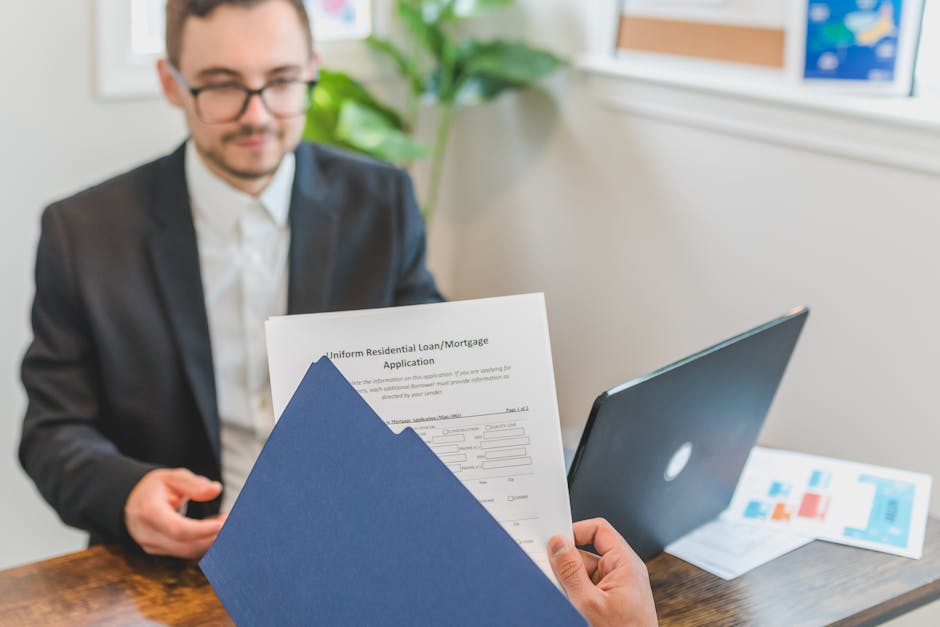
A loan package is a single organized file a lender reads to decide whether to say yes. Your job is to make that decision easy. Lenders weigh the same handful of things every time: cash going in, repayment ability, credit history, collateral, and a plan. The package is simply the evidence for those five.
Table of Contents
- What does a lender actually look for in a loan package?
- What documents go into a small business loan package?
- What should the written portion of the package say?
- How far back should your financial history go?
- How do you match the loan type to how the money will be used?
- How do you assemble and submit the package without delays?
- How does Spencer Accounting Group help business owners prepare for a lender?
- Key Takeaways
- References
What does a lender actually look for in a loan package?
A lender works through five underwriting questions: how much is requested, what the money will do, how it gets repaid, what happens if repayment fails, and what the owner is putting in. The package exists to answer those questions with documents and a written plan.
Every lender has its own eligibility and application requirements, but most look for the same basics, according to the Minority Business Development Agency. Those basics are personal and business credit reports, bank statements, financial statements, and a business plan.
There is no such thing as 100% financing. The SBA training course on loan packages states plainly that a borrower will be required to put money into the business before a lender provides financing.
Some lenders recognize sweat equity as a contribution to owner's capital. That means unpaid work already invested in the business can count toward the owner's required stake.
A personal guaranty is commonly requested even when the business is incorporated. The SBA course notes that a lender will probably ask for one, which means the owner's personal assets stand behind the loan.
What documents go into a small business loan package?
The document list splits into four buckets: entity and ownership records, financial statements, tax returns, and bank statements. Start with those four groups and build outward from what the lender asks for.
Tax returns carry the most weight. Most loan programs require personal and business income tax returns for the previous three years, according to the Minority Business Development Agency. Some lenders ask for two to three years depending on the loan type, according to Midwest BankCentre.

Bank statement requirements vary by lender. Many loan programs require one full year of personal and business bank statements. Others ask for the past three to six months of business statements only.
Owners holding more than a 20% stake in the business are often required to submit signed personal financial statements. That requirement applies across many loan programs.
If the business is self-employed or has irregular or nonwage income, additional documentation is usually required, according to the Consumer Financial Protection Bureau. Expect to show more evidence of income stability in those cases.
What should the written portion of the package say?
The written portion should cover seven elements lenders expect in the narrative: executive summary, business description, market analysis, management and organization, product or service line, sales and marketing, and financial projections. That list comes from Woodsboro Bank.
Quantify achievements rather than describing them. Woodsboro Bank gives the example: "Our customer base grew by 30% in 2022." A number carries more weight than an adjective.
A sound business plan is required across loan programs, according to the Minority Business Development Agency. The plan must include a complete set of projected financial statements covering profit and loss, cash flow, and balance sheet.
Common mistakes weaken the written portion. Woodsboro Bank flags vagueness, skipped proofreading, thin research, over-optimism, and omitting an exit strategy as frequent problems.
False or misleading information will result in the loan being denied. The Minority Business Development Agency states that outright. Accuracy matters more than polish.
How far back should your financial history go?
Lenders want both historical statements and projections because each answers a different question. History shows how the business has actually performed. Projections show where the owner expects it to go and whether the loan fits that path.
Include the last three to five years of income statements, balance sheets, and cash flow statements when available, according to Woodsboro Bank. Older businesses should provide the full range.
For a new business with no operating history, provide detailed financial projections instead. The projections replace the missing track record.
Projections must cover profit and loss, cash flow, and balance sheet, not just a revenue line. The Minority Business Development Agency specifies that complete projected financial statements are part of a sound business plan.
How do you match the loan type to how the money will be used?
Match the loan type to the use of funds before assembling the package. Lenders evaluate working capital and growth capital differently because the repayment sources differ.
Working capital is money used to meet fluctuating needs, repaid during the company's next full operating cycle, generally one year, according to the SBA training course. It covers short-term gaps like inventory or payroll timing.
Growth capital is money used to meet needs repaid out of profits over a set period, usually not more than seven years, though some SBA financing options allow longer maturities. Growth capital funds expansion, equipment, or market entry.
Typical maturities follow the use. Working capital loans and lines of credit usually run under one year. Asset-based and equipment loans typically run three to seven years. SBA-guaranteed loans can exceed ten years.
The SBA does not lend money directly to small businesses except for disaster assistance. It acts as a guarantor of loans made by lenders to small firms.
There is no government grant for individual small businesses. No government source, including the SBA, provides free money to open or grow a for-profit small business.
How do you assemble and submit the package without delays?
Build the package from a single master document list so nothing is gathered twice. One list keeps the process linear and prevents duplicate requests from slowing things down.
Incomplete documents may be rejected outright, according to the Consumer Financial Protection Bureau. A missing page can stop the review before it starts.
Expect to update the package at least once during the process. The Consumer Financial Protection Bureau states that chances are the borrower will need to refresh the loan application packet before closing.
Some lenders use technology to pull account information directly from banks or employers to verify income or employment. That automation can shorten the collection step.
Proofread and format consistently before submission. Woodsboro Bank notes that presentation affects how the numbers are read, and sloppy formatting can undercut strong financials.
How does Spencer Accounting Group help business owners prepare for a lender?
Spencer Accounting Group gets the numbers lender-ready before the application goes in, not after a denial. The work starts with clean books and current filings, because those are the documents every lender asks for first.
Bookkeeping keeps monthly books clean and reliable year round. That means the financial statements a lender requests already exist and do not need to be reconstructed under deadline.
Strategic Tax Planning designs the tax position around where the business is heading rather than discovering it in April. A forward-looking tax position makes the historical returns a lender reviews more coherent.
Tax Filing prepares and files business and individual returns on time through a secure portal, from anywhere in the world. Filed returns are a baseline requirement in most loan packages.
For owners behind on returns, Back Tax Return Filing sequences catch-up work to reach compliance with the least disruption. Most loan programs require multiple years of filed returns, so missing years block the application before it starts.
Spencer Accounting Group is 100% virtual and serves clients in any state or country. No office visit is required.
Key Takeaways
- A loan package is the evidence file for five underwriting questions: amount, purpose, repayment, risk, and owner contribution.
- There is no such thing as 100% financing; lenders require the owner to put money into the business.
- Some lenders count sweat equity toward owner's capital.
- A personal guaranty is commonly requested even when the business is incorporated.
- Most loan programs want three years of personal and business tax returns; some lenders ask for two to three years depending on loan type.
- Owners holding more than a 20% stake are often required to submit signed personal financial statements.
- Incomplete documents may be rejected, and the package usually needs at least one update before closing.
Note: This article is general information, not tax advice for a specific situation. Filing deadlines shift year to year and should be confirmed for the current tax year. To see whether this is a fit, book a consultation with Spencer Accounting Group.
References
- How to Prepare a Loan Package — SBA training course, date unknown
- Create a loan application packet — Consumer Financial Protection Bureau, December 12, 2024
- What to Include in a Small Business Loan Request Package — Woodsboro Bank, date unknown
- Loan Documentation — Minority Business Development Agency, date unknown
- How to Prepare for a Business Loan: What You Need to Know — Midwest BankCentre, April 30, 2025